One property. One buying brief.
A purchase-only engagement centres on finding a property, negotiating the price and reaching settlement. Your wider portfolio strategy and what comes next sit outside that brief.
- Find
- Negotiate
- Settle
Investing in property before you retire
Your home, super and income are a starting point. Your licensed adviser assesses the time and assets you have and sets the retirement plan. We buy established, easier-to-hold property that fits it, and review it with you as retirement gets closer.

850+ five-star Google reviews. REB Buyer's Agency of the Year, winner 2023, 2024 and 2026.
Our customer success has been featured in 1000+ media and news outlet articles.
In the newsSound familiar?
You own a home, maybe one investment, and retirement is now a date rather than an idea. It feels as if the window is closing.
There is less time to recover from a poor purchase than there was at 30. You do not want to lose the equity you have built.
Before another large decision, you want to know the risks and the options in plain words.
Super, borrowing through an SMSF and capital gains tax have all changed in 2026. You are not sure what applies to you.
What is really going on
Your home, your super, any investment property and your borrowing are usually handled by different people at different times. Working backwards from when you want to retire, with your adviser setting the goal and the level of risk, turns those pieces into one plan. Our part is buying property that fits that plan and checking it still fits as the years go by.
Who does what
InvestorKit does not provide financial, tax, legal or credit advice, or advice on how to fund your retirement.
How we help before retirement
Five steps, each one coordinated with the professionals who advise you.
A 15-minute conversation about your timeline, what you own now and where your advice is up to. If you have not spoken with a financial adviser, we will suggest that first.
Your adviser decides whether property fits your retirement plan and the level of risk. Your broker confirms the lending. Within those limits, we agree a property brief with you.
We research nationally for established property with sound construction and steady rental demand, so it asks less of you as the years go by.
Every shortlisted property goes through our 20-point due diligence. We negotiate the price, and nothing is bought without your agreement.
Portfolio reviews are part of the engagement, so we can check the portfolio still fits as your plans, the market and the rules change.
Why a buyer’s agent and wealth partner
There is less time to recover from a poor purchase than there was at 30. Your adviser sets the plan and the level of risk, and we research, check and buy property that fits it.

Suburb research, inspections, agent calls and paperwork can take months of evenings and weekends. We carry that work, and you make the decisions.

Our research team studies supply, demand, rents and local conditions nationally, so the shortlist is not limited to the suburbs you already know.

Every shortlisted property goes through our 20-point due diligence checklist, and we coordinate inspections before you are asked to commit.

The selling agent works for the vendor. We negotiate the price and terms for you, with the research behind every offer.

Around 70% of our recent purchases were off-market or pre-market, so the search reaches past what is listed online.

Your Portfolio Wealth Blueprint maps what comes next across residential and commercial property, and we connect you with selected finance, accounting and insurance professionals along the way.
It is a paid service, and it does not suit everyone. We confirm our fee with you upfront, and the free discovery call is where we check together that it fits your budget and your plan.
The InvestorKit difference
A property purchase is one step. We help you build a portfolio around your goals, and keep reviewing the plan with you as it grows.
A purchase-only engagement centres on finding a property, negotiating the price and reaching settlement. Your wider portfolio strategy and what comes next sit outside that brief.
The InvestorKit Group is your wealth engine room. Start with your Portfolio Wealth Blueprint, put it to work through residential and commercial investing, and keep reviewing the plan as your portfolio grows. We connect you with selected finance, accounting and insurance professionals along the way.
Here for one purchase? We can help with that too. Start with the support you need, with room to build a longer-term partnership.
Purchase-only scope shown. Services vary by agency and engagement.
Why InvestorKit


REB Buyer's Agency of the Year, winner 2023, 2024 and 2026.

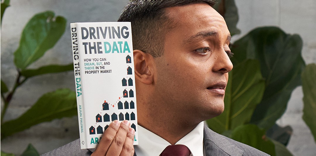
Strategists, researchers and buyers’ agents work together on every brief. The research team studies markets nationally and publishes its thinking in whitepapers, reports and the book Driving the Data.
No developer commissions and no selling agent referral fees. We confirm our fee with you upfront, so our advice follows your plan.
$2B+ in property purchased for clients, and 850+ five-star Google reviews.
In the conversation
Forbes Australia BrandVoice partner content
On Today Extra
Author of Driving the DataExperience behind the approach
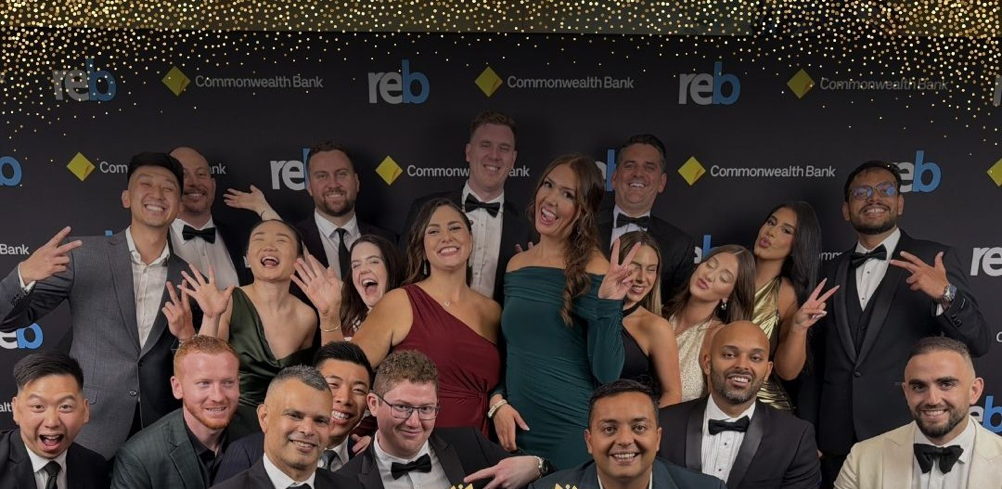
Meet our clientsDated company experience. Purchase counts and reach are historical; individual outcomes vary and are not a forecast of your results.
A fair question
We can’t answer that honestly without your numbers, and whether property suits your retirement is a question for your licensed financial adviser. What we can say is that it depends on your equity, borrowing, income and how many working years you have, not on age alone. Some of our clients started after 45. On a first call we look at where you are, and if property isn’t the right next step, we will say so.
Your next step
Tell us where you are and what you want. We will explain how we work and whether we are the right fit. You do not need to be ready to buy.
The discovery call suits people with access to at least $125K in savings or equity, or guarantor support.
Free 15-minute call. No obligation.
850+ five-star Google reviews. REB Buyer's Agency of the Year, winner 2023, 2024 and 2026.
Rules and policy
Current at . General information, not financial, tax or legal advice. Check how any change applies to you with your accountant or adviser.
Law, not yet startedFederalFrom
For gains that build up from 1 July 2027, the 50% capital gains tax discount is replaced by indexing the cost base to inflation, plus a 30% minimum tax on the real gain. Gains built up before that date keep the 50% discount, and main residences stay exempt.
Source: ATO: negative gearing and CGT reforms (opens in a new tab), Budget 2026-27 explainer (PDF) (opens in a new tab)
In forceFederalFrom
Since 10 August 2026, a self-managed super fund cannot enter a new limited recourse borrowing arrangement to buy residential property. New borrowing for real property must be for business real property. Existing arrangements continue, and SMSFs can still buy residential property with cash.
Source: ATO: changes to limited recourse borrowing arrangements (opens in a new tab), ATO SMSF news: changes from 10 August (opens in a new tab)
In forceFederalFrom
From 1 July 2026, people with a total super balance above $3 million pay an extra 15% tax on the share of their fund’s realised earnings linked to the balance above $3 million, and a further 10% above $10 million. Unrealised gains are not taxed.
Source: ATO: better targeted superannuation concessions (opens in a new tab), ATO: Division 296 thresholds (opens in a new tab)
Draft for consultationFederal
Treasury has released draft law for a 30% minimum tax on income from discretionary (family) trusts, planned to start on 1 July 2028. It is a draft for consultation only, is not law and could change before it reaches Parliament.
Source: ATO: minimum tax on discretionary trusts (opens in a new tab), Treasury consultation (opens in a new tab)
Is this you?
The discovery call suits people with access to at least $125K in savings or equity, or guarantor support.
Before you decide