Commercial buyer's agent Buy the income, not the headline yield.
Commercial property for investors who want income backed by a tenant and a lease. Chris Huxter, Buyers Agent of the Year, Commercial, at the 2026 Australian Buyers Agent Awards, leads the search, the checks and the negotiation. You keep the final say.
Residential builds the base. Commercial can turn it towards income. Some portfolios start residential and add commercial when the plan calls for income.
Residential
The job: long-term growth
What you buy
Established houses in growth markets, ready for tenants
Typical budget
From $525,000, or $575,000 through an SMSF
What drives the return
Capital growth from land and local demand, over many years
Commercial is not necessarily riskier than residential. It is less forgiving of a poor decision, which is why every deal must pass four tests before we recommend it.
Your capital, income goal and risk tolerance set the brief. We model the borrowing costs, cashflow and cash needed to settle before the search begins, so you know what a property has to earn before you see one.
Illustrative $3M purchase
Seewhattheincomeneedstocover.
In this example, $15,000 in monthly net rent covers $11,375 in interest, leaving $3,625 before other costs and tax. Your plan tests how the numbers work for you.
A $3M purchase at 6% net yield, with a $2.1M loan covering 70% of the price and 6.5% interest-only lending.
Net rent per month
$15,000
Interest per month
$11,375
After interest per month
$3,625
Scroll to compare all three figures.
$0Monthly amounts, same dollar scale
Illustrative only, assuming full rent collection. The monthly figures exclude principal repayments, land tax, capital expenditure, other holding costs and tax effects. Confirm lending, costs and structure with your qualified advisers.
Buying costs vary by property and state. A cash buffer sits on top of the deposit and buying costs.
The asset type, target markets and buying criteria shaped around your income goal.
Cashflow modelling
Cashflow modelling over 10 years, comparable evidence and funding scenarios before you decide.
Capital deployment
The capital available to invest, what to retain and how the purchase fits your broader portfolio.
Strategic steps
The borrowing, timing and portfolio decisions to work through before purchase.
Your commercial plan is developed as part of the engagement. The free discovery call is the first conversation about your goals and how we can help.
The commercial perspective
Theyieldisonlythestartingpoint.
Your next property should have a clear job in your portfolio. Commercial can provide rental income supported by the tenant, the lease and the asset itself.
Finance costs, vacancy and the expenses that remain with the owner all affect what reaches you. We assess those factors alongside the income the property could provide.
The goal is to understand how the acquisition fits your plan, what supports its income and what could interrupt it.
A national individual title, judged on Chris's own performance and process against commercial buyer's agents across Australia. It recognises the person who leads your acquisition, not the agency brand.
Chris brings experience in acquisitions, valuations and leasing at Lendlease and Mirvac to your commercial purchase. A dedicated team works across research, sourcing, due diligence and settlement, with the reasons for the recommendation made clear to you.
institutional portfolio previously managed
$2.2B
lease renegotiations across Mirvac and Lendlease portfolios
1,000+
From Chris's career before InvestorKit.
Senior Acquisitions Analyst Kim Vo brings a double degree in Law and Finance to the team, supporting lease assessment and contract negotiation.
Research and sourcing
Market intelligence, property sourcing and hazard screening across target asset classes.
Acquisitions
Due diligence, negotiation and contract coordination through to exchange.
Modelling and analysis
Cashflow modelling over 10 years, comparable evidence and funding scenarios.
Settlement and client success
Settlement coordination, property management introductions and ongoing portfolio reviews.
On your side of the transaction.
We act for the buyer. Our fee is paid by you, with no selling-agent or vendor commissions.
Each test helps assess the risks of vacancy and unexpected capital expenditure. A higher yield only tells part of the story.
01
Vacancy risk
Locationandmarket
Will the market keep this asset leased if the tenant leaves?
Demand, vacancy, future supply, rental growth and access. We assess who could replace the current tenant.
02
Capital expenditure risk
Assettypeandcondition
Will the building remain financeable, insurable and useful?
Our focus is industrial, medical and essential retail. Building condition and competing supply matter as much as the headline yield.
03
Income risk
Tenantstrength
Who is actually promising to pay the rent?
Trading history, financial strength, arrears and reliance on the location. On-site inspections and tenant interviews inform the assessment.
04
Income and vacancy risk
Leasestrength
How secure, recoverable and durable is the income?
Lease length and WALE (the weighted average lease expiry across every lease), rental reviews, outgoings, options, make-good obligations and guarantees. We examine the terms behind the rent.
You should understand why an asset qualifies, the trade-offs involved and what would change the recommendation.
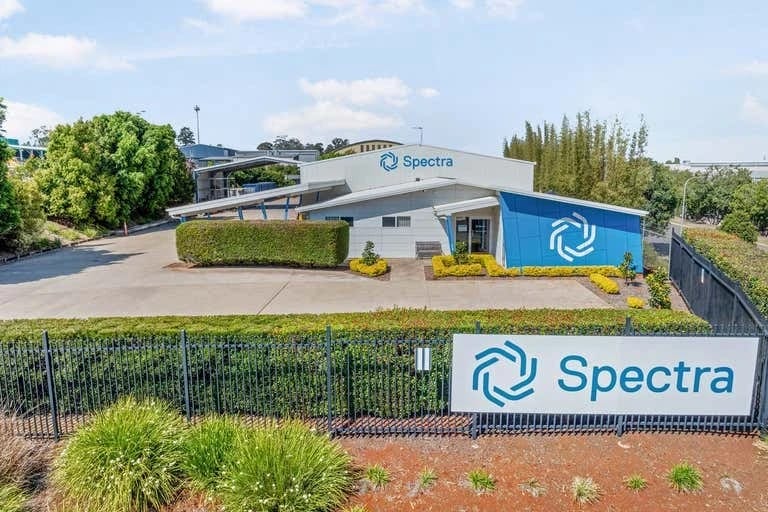
A national tenant in Queensland, an off-market find in Victoria and a five-year net lease in New South Wales. Each card shows the terms we secured and why the asset qualified.
National tenant
Harristown, QLD
Queensland industrial
Net yield at purchase
6.25%
Purchase price
$4,000,000
A national tenant and $250,000 in net annual rent supported this Queensland industrial acquisition. Negotiation reduced the $4.2M asking price by $200,000, bringing the purchase price to $4M.
Asking price
$4,200,000
Saved on negotiation
$200,000
Net annual rent, year 1
$250,000 p.a.
Net cashflow after IO interest
$75,000 p.a.
Return on equity
5.02%
Cashflow is after interest-only payments. Lending assumptions and cost inclusions are not specified for this example. Return on equity depends on the capital contributed.
Off market
Ballarat, VIC
Victoria industrial
Net yield at purchase
6.10%
Purchase price
$3,450,000
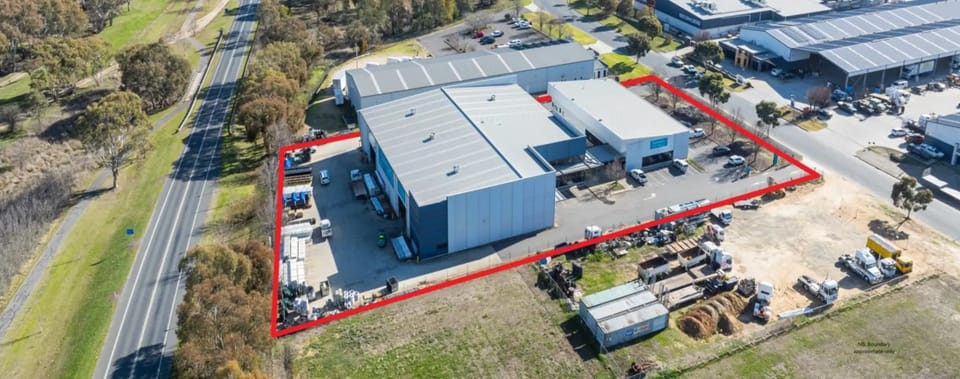
An off-market search reached this industrial asset in a tightly held regional market. At purchase, it carried $210,545 in net annual rent. The rent and acquisition price provide the basis for its 6.10% net yield.
Net annual rent, year 1
$210,545 p.a.
Net cashflow after IO interest
$77,720 p.a.
Return on equity
6.39%
First year total return, forecast
$215,720 · 17.74%
Cashflow is after interest-only payments. Lending assumptions and cost inclusions are not specified for this example. Return on equity depends on the capital contributed. Forecast total returns are estimates, not realised returns.
National plumbing tenant
Albury, NSW
New South Wales industrial
Net yield at purchase
6.09%
Purchase price
$5,100,000
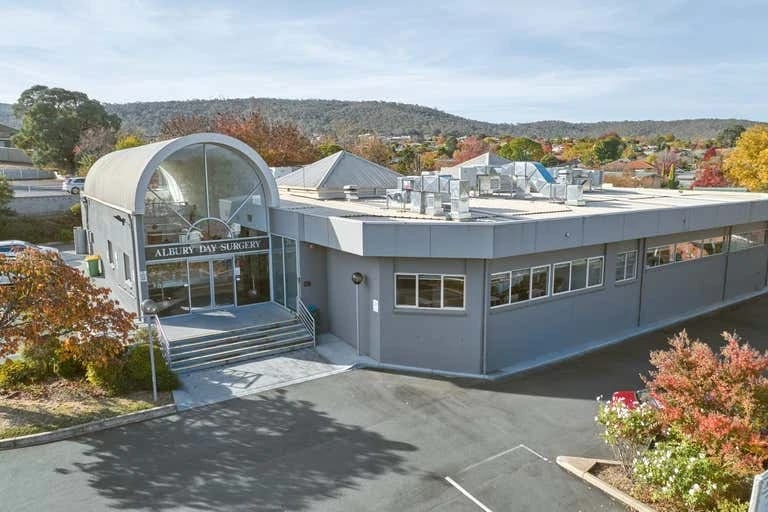
After a previous commercial property sat vacant for two years, an experienced investor engaged InvestorKit for their next acquisition. The Albury industrial asset combined a national plumbing tenant with a five-year net lease. We secured it for $5.1M at a 6.09% net yield.
Saved on negotiation
$100,000
Net cashflow after IO interest
$114,050 p.a.
Return on equity
5.92%
First year total return, forecast
$318,050 · 16.51%
Lease
5 year term, annual review, net lease
Tenant
National plumbing group, 47 years, 6 locations
Cashflow is after interest-only payments. Lending assumptions and cost inclusions are not specified for this example. Return on equity depends on the capital contributed. Forecast total returns are estimates, not realised returns.
Selected acquisitions. Forecast figures are labelled in each example.
Due diligence in action
Wewalkedawayfrom7%.Weboughtat6.3%.
Two properties, two decisions, the same checks. The higher yield hid a roof and air-conditioning problem. The lower one came with a tenant on site since 2005.
Walk awayDeal rejected
Thedealwewalkedawayfrom
West Albury, NSW
The offer on paper
Listed price
$6,600,000
Advertised net yield
7.0% net
Passing net income
$466,722 p.a.
Lease term
7 year lease to 2032
What the checks uncovered
The on-site inspection identified significant roof leaks requiring replacement. The HVAC system would need to be removed and reinstated to complete the work. The client exited under the due diligence clause, avoiding estimated remediation costs of $500,000 to $600,000.
Roof leaks requiring replacementHVAC removal and reinstatement
The value of walking away
$500k to $600kEstimated remediation cost avoided
The client exited the deal.
Move forwardProperty acquired
Aclearerplan.ABrisbaneacquisition.
Brisbane, QLD / Industrial
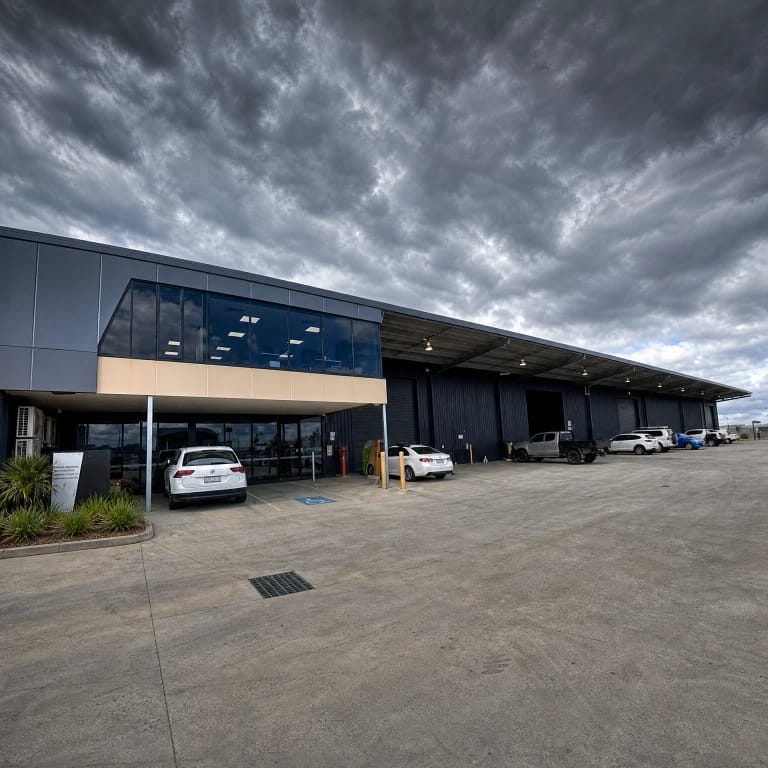
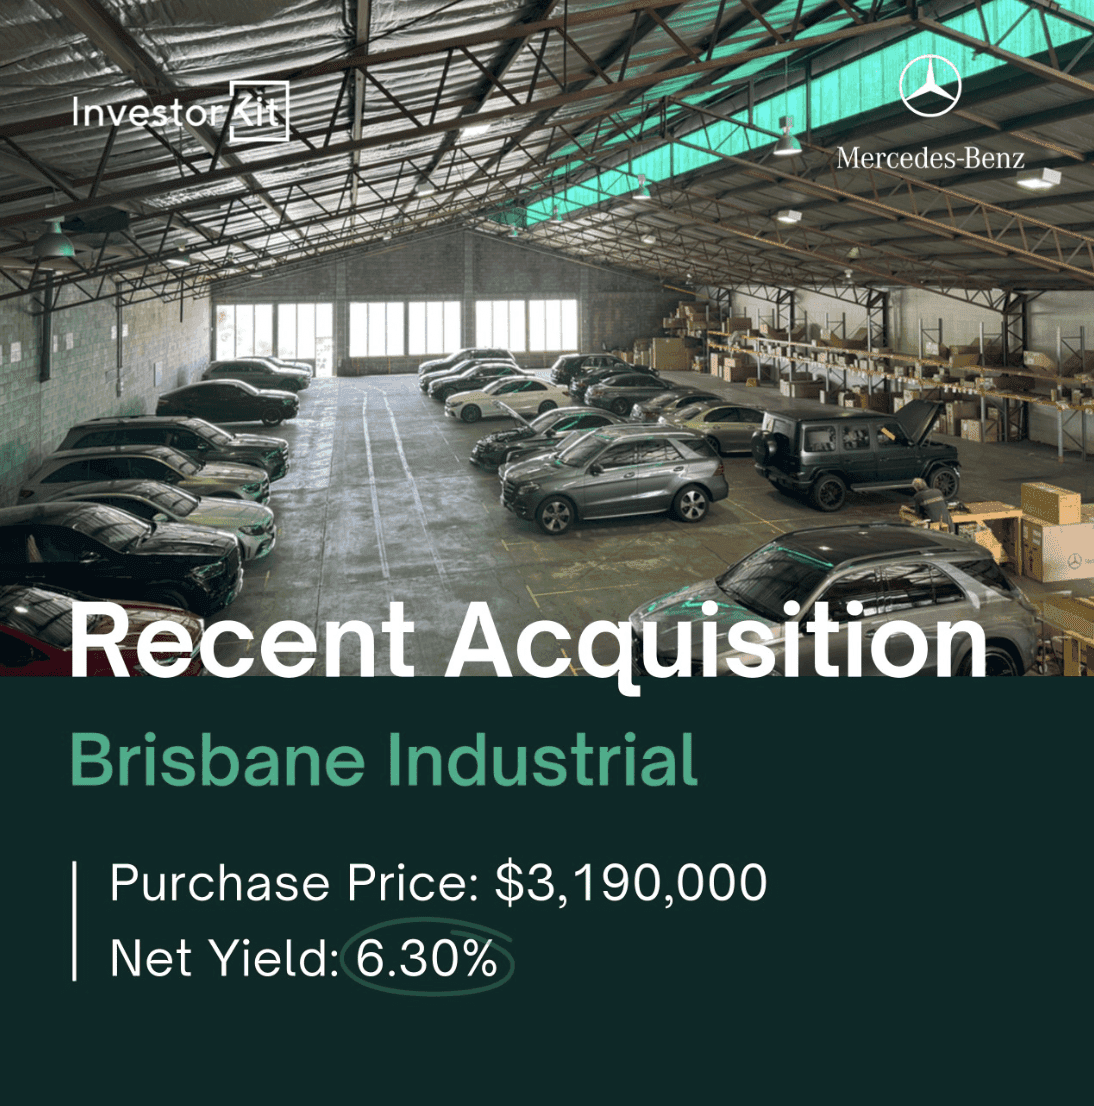
A high-income investor wanted to understand commercial property and the lease risks before buying. We developed a plan, explained the assessment and supported the acquisition. The Brisbane industrial property paired an established tenant with a new lease and scheduled rent increases.
Why this asset made sense
Mercedes-Benz Brisbane had occupied the site since 2005
The tenant also owned the neighbouring site
The property supported vehicle storage and logistics
An industrial location near Brisbane CBD
The outcome
Net yield at purchase
6.30%
Purchase price
$3,190,000
Net annual rent at purchase
$201,000 p.a.
Tenant
Mercedes-Benz Brisbane
Lease
New 3-year lease with a 3-year option; 4%+ annual increases
Purchase figures for this Brisbane acquisition. Rental income is before finance costs. Lease options are exercisable by the tenant.
Each started somewhere different. Each wanted the portfolio to pay for more of their time. Their stories are published in full.
Jasmine
Moved to Australia from France
1 dealwhose income covered her living expenses
Jasmine started in residential, then chose commercial for reliable income. Her asset sits in a blue-chip part of a major city, with a national tenant and CPI-linked rent reviews. The income covered her living expenses and gave her room to study again.
$200k+net annual income from five commercial assets, as he shared on our podcast
Michael began with residential in major cities, added regional markets, then moved into commercial as his business income grew. With our guidance, his portfolio grew to 13 properties, residential and commercial, across five states.
$9M+portfolio across four states, now turning towards commercial
Raj and Sowji built eight residential properties across four states with us. The next phase of their plan is commercial property and unit blocks: cash flow from day one, while the residential base keeps growing.
Individual client results. Past performance does not guarantee future results.
How we work together
Sevenstepsfromstrategytosettlement.
Set the brief. Assess the opportunity. Make an informed decision.
We handle the research, sourcing, assessment and acquisition coordination. You shape the brief, review the recommendation and decide whether to proceed.
Opportunities pass our initial filters before recommendation. Detailed inspections, lease reviews and specialist checks follow under the due diligence clause, before the purchase becomes unconditional.
Your goals, capital, income target and acquisition brief.
02
Research
Qualify the market, asset class and location.
03
Sourcing
Search on-market, pre-market and off-market opportunities.
04
Initialduediligence
Before exchange: desktop assessment of the market, asset, tenant, lease and financial position before a deal is presented.
05
Detailedduediligence
Under the agreed due diligence clause: on-site inspection, tenant interviews where possible, lease review and specialist checks before the purchase becomes unconditional.
06
Settlement
Coordinate legal, finance, insurance, building inspection and property management support through settlement.
07
Partnership
Property management introductions, annual portfolio reviews and ongoing strategy after settlement.
Not necessarily, but it is less forgiving. If a tenant leaves, the income can stop while loan and holding costs continue, and a specialised building can take longer to re-lease. One investor came to us after a previous commercial property sat vacant for two years. That is why every opportunity must pass our four tests on the market, the building, the tenant and the lease before we recommend it.
Commercial purchase budgets typically start from $2M and can exceed $10M. The budget is one part of the picture: the deposit, transfer duty, buying costs and a cash buffer all affect the capital required. In the illustrative example on this page, a $3M purchase with a 70% loan needs about $1.11M to settle, before a buffer. Your finance adviser can confirm borrowing capacity and lender requirements; these inputs help shape the acquisition brief.
The property, tenant, lease and your financial position can all affect the lending terms available. We consider the borrowing pathway and indicative cashflow before the search. Your broker or lender confirms the finance terms for your circumstances. Equity in an existing property may also form part of the funding, subject to lender approval.
WALE stands for weighted average lease expiry: the average time left on a property's leases, weighted by rent or floor area. On a single-tenant property it is simply the time left on the lease. A longer WALE with a strong tenant gives the income more certainty, and lenders and future buyers look at it too. We test it alongside the tenant's strength and how easily the market could re-lease the space.
The lease sets out which outgoings the tenant pays and which remain with the owner. We review those obligations alongside the property's condition, so maintenance and potential capital costs form part of the assessment.
Rental income may stop while ownership and finance costs continue. Our assessment looks at replacement tenant demand, competing supply, the condition of the building and the lease terms. Those checks help you understand vacancy risk and the cash reserves the investment may need.
It can be an option if your fund's investment strategy allows it. Since 10 August 2026, an SMSF cannot enter a new limited recourse borrowing arrangement to buy residential property, but it can still use one for business real property, such as commercial premises. Your SMSF specialist, accountant or lender confirms how the rules apply to your fund before the search begins.
It often does. A tenanted commercial sale may be GST-free as a going concern, but only when every requirement is met: both parties are registered for GST, they agree in writing that the sale is a going concern, and the seller keeps the leased enterprise running until settlement. If any requirement is missed, GST can apply on top of the price. The contract states how GST applies, and your accountant confirms the treatment for your structure before you sign. We raise it during the contract review.
We focus on industrial, medical and essential retail across Australia, including warehouses, logistics facilities, healthcare property and daily-needs retail. Suitability depends on your goals, capital and risk tolerance. Every recommendation is assessed against the market, building, tenant and lease.
The engagement covers commercial strategy, research, sourcing, due diligence and acquisition support. We are paid by the buyer, with no selling-agent or vendor commissions. An upfront retainer starts the engagement, with the balance payable on unconditional exchange. Your agreement sets out the fee, scope and payment stages.
Yes. Our commercial team coordinates national market research, sourcing, on-site inspections, tenant and lease checks, negotiation and settlement. You can invest from interstate, stay informed and retain the final say on the purchase.
Timing depends on your capital, borrowing position, investment horizon and the opportunity itself. We assess tenant demand, vacancy, supply and lease conditions alongside your plan. The aim is to find a suitable acquisition when the brief and the fundamentals align.
We discuss your capital, income goal and where commercial could fit in your portfolio. You can ask about the process, fees and next steps. It is an initial conversation about fit; the commercial plan and modelling are developed as part of the engagement.
We help coordinate the handover and introduce property management support. The relationship continues through annual portfolio reviews and ongoing strategy, so the asset remains part of a broader plan. We also help you understand the roles of the property manager, lender and your professional advisers.
Speak with the commercial team
Startwithyourcommercialplan.
Bring your capital, your income goal and your questions. On a free discovery call, our commercial team talks through where commercial could fit in your portfolio, the work involved and the next step.
The first call helps establish fit and next steps. Your commercial plan and modelling form part of the engagement.