Key takeaways
- InvestorKit believes the markets most exposed to investor tax reform and weaker borrowing are those where investor reliance, stretched borrowing, compressed yields and high supply overlap.
- InvestorKit argues the proposed tax reforms are not creating vulnerabilities, but are increasing pressure on markets where those vulnerabilities already exist.
- InvestorKit notes that affordable investment markets with stronger rental yields may prove more resilient, as owner-occupiers and first-home buyers can partly replace investor demand.
As discussion around investor tax reform intensifies, many property investors are starting to ask a more important question:
Which property markets could be most vulnerable if investor borrowing power weakens and tax incentives become less favourable?
At InvestorKit, we believe the answer isn’t simply “investor-heavy suburbs”.
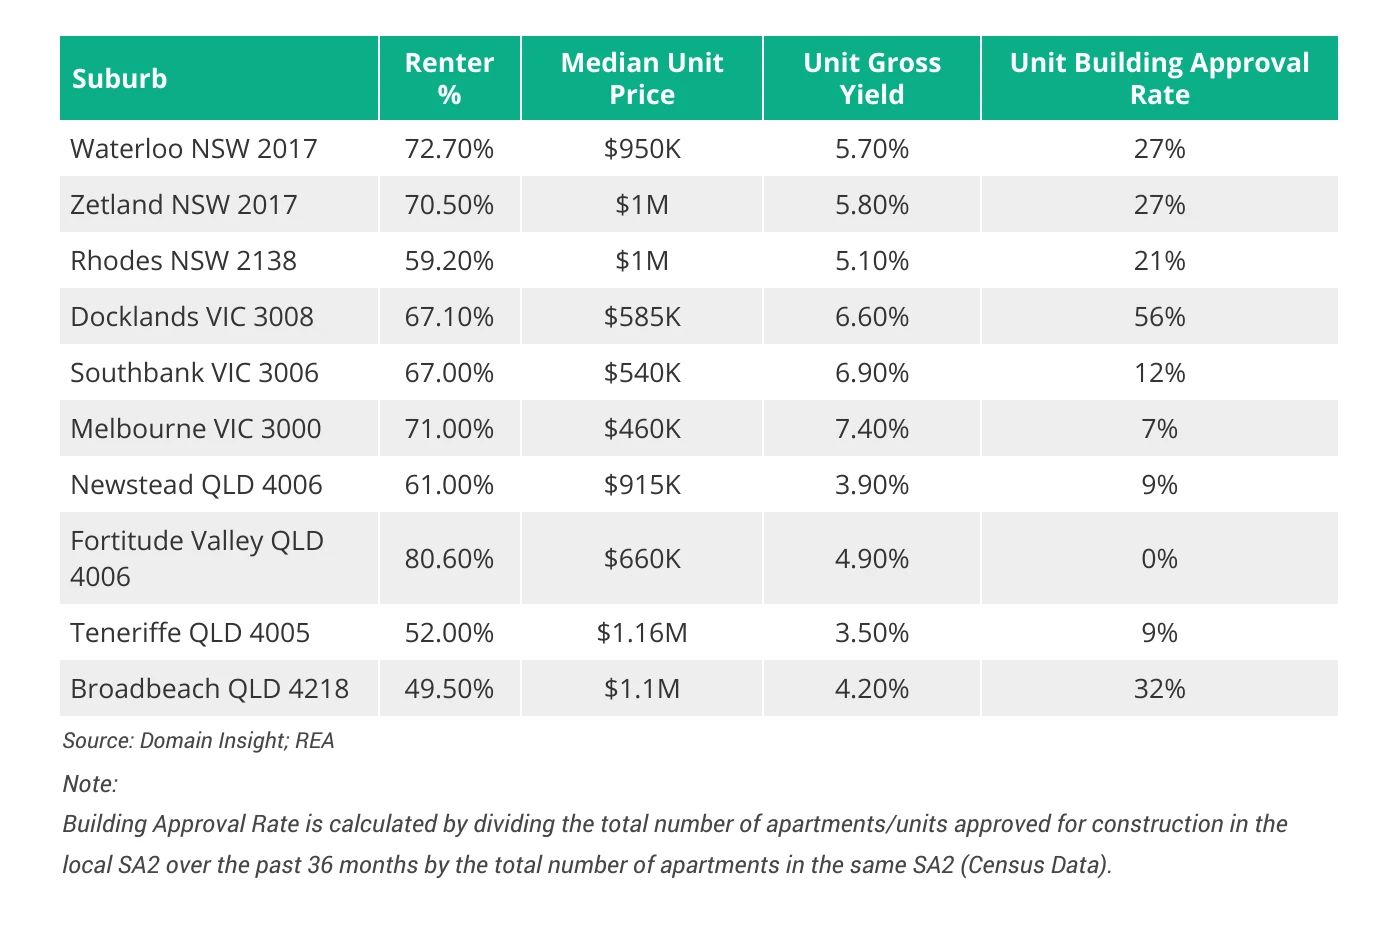
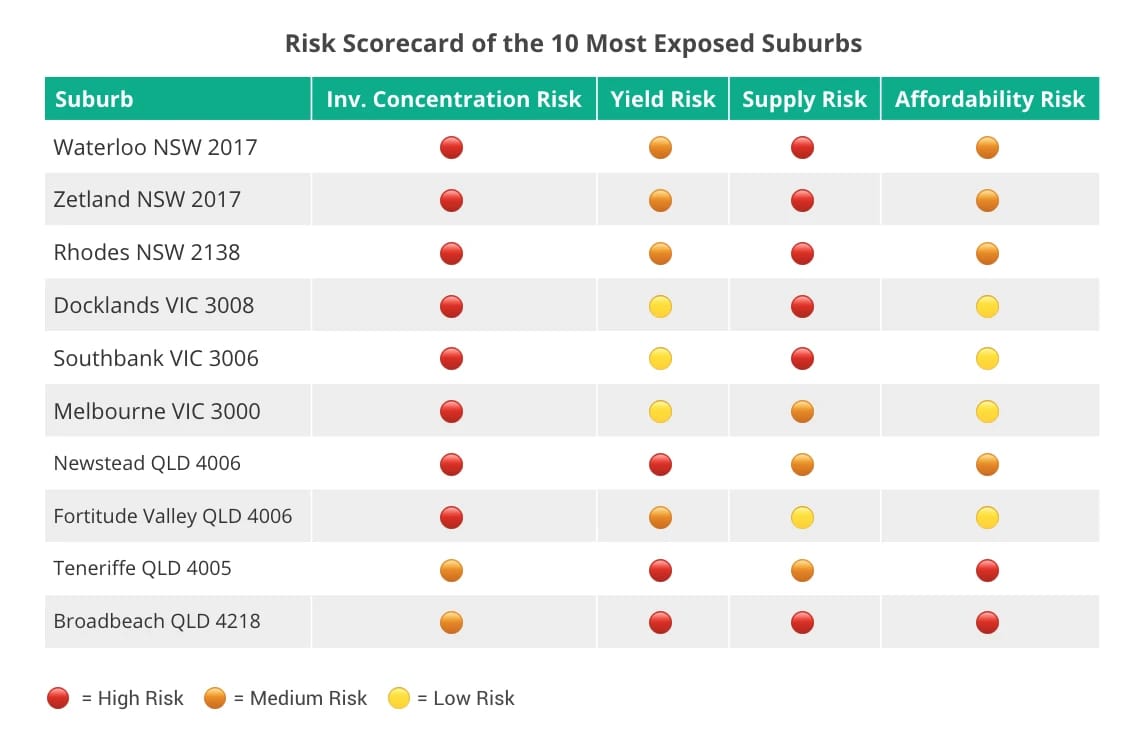
The markets most exposed are those where several risk factors overlap at the same time, particularly where heavy reliance on investor demand, stretched borrowing capacity, compressed yields, and high volume of supply all combine.
The 4 Risk Factors We’re Watching
When assessing which suburbs may be most sensitive to investor tax reform and reductions in borrowing capacity, we focus on four key indicators.
1. High Investor Participation
Markets where investors account for a significant share of buyers are naturally more exposed to changes in lending conditions, tax policy, and borrowing capacity.
If investor sentiment weakens, these markets can lose a major source of demand very quickly.
2. Lower Rental Yields
Low-yield investment markets often rely more heavily on capital growth expectations and tax benefits to justify holding costs.
This makes them more vulnerable if tax advantages are reduced or borrowing becomes more expensive.
3. Elevated Supply Risk
Apartment-heavy precincts with large development pipelines can already face supply pressure.
If investor demand softens while more stock continues to enter the market, resale competition can intensify, placing downward pressure on prices and rents.
4. High Prices Stretch Borrowing Capacity
Higher-priced investment markets require greater leverage, making them especially sensitive to reductions in borrowing capacity.
Even relatively modest changes in lending can materially reduce buyer demand in these locations.
The 10 Suburbs Most Exposed
Based on these combined factors, we believe the following suburbs could be among the most exposed nationally if investor tax reforms and lending changes reduce investor activity:
These Risks Have Historically Impacted Performance
It’s important to note that the proposed tax reforms are not creating vulnerabilities. They are simply increasing pressure on markets where those vulnerabilities already exist
In many of our selected suburbs, heavy reliance on investor demand, elevated apartment supply and poorer affordability have already influenced performance in a number of these markets over the past decade.
The chart below compares the unit market performance of a high-price, high-supply and investor-dominated apartment market, Zetland, against a moderate-price, moderate-supply and owner-occupier-driven (renter % = 32%) unit market, Croydon Park.
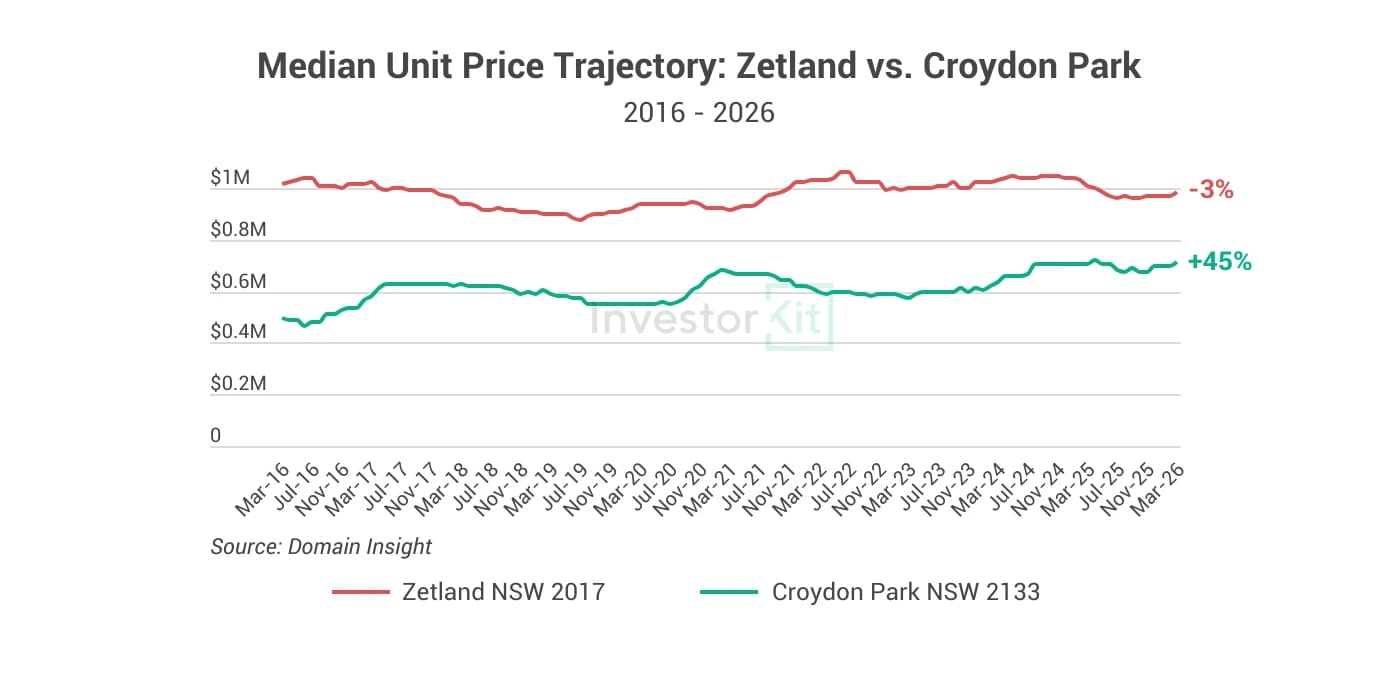
Despite experiencing periods of price volatility, Croydon Park’s unit market has delivered much stronger long-term growth than Zetland’s. Of course, we’re only discussing unit market performance here, not considering the performance gap between asset types.
The comparison highlights an important point: the characteristics that make some suburbs more exposed to policy and lending changes today are often the same ones that have historically constrained growth.
Not All Investor Markets Are Equal
It’s worth noting that not all investor-heavy markets are equally vulnerable.
Affordable investment markets with stronger rental yields may prove more resilient because owner-occupiers and first-home buyers can partially replace investor demand if conditions soften.
Similarly, many premium house markets remain predominantly owner-occupier driven, reducing their direct exposure to investor lending or tax-policy changes.
The Australian property market is not one market. It’s thousands of micro-markets responding differently to supply, lending conditions and buyer demand.
That’s why broad headlines about “property risk” often miss the nuance.
At InvestorKit, we believe investors should focus less on speculation and more on understanding where risks are concentrated, particularly in markets where supply, leverage and investor dependency all intersect. Because in changing market conditions, selecting the right asset in the right location becomes even more important.
Concerned about where investor policy changes could create risks or opportunities in the market? Book a free discovery call with InvestorKit to learn about the data-driven approach we use to identify resilient, high-performing investment locations across Australia.